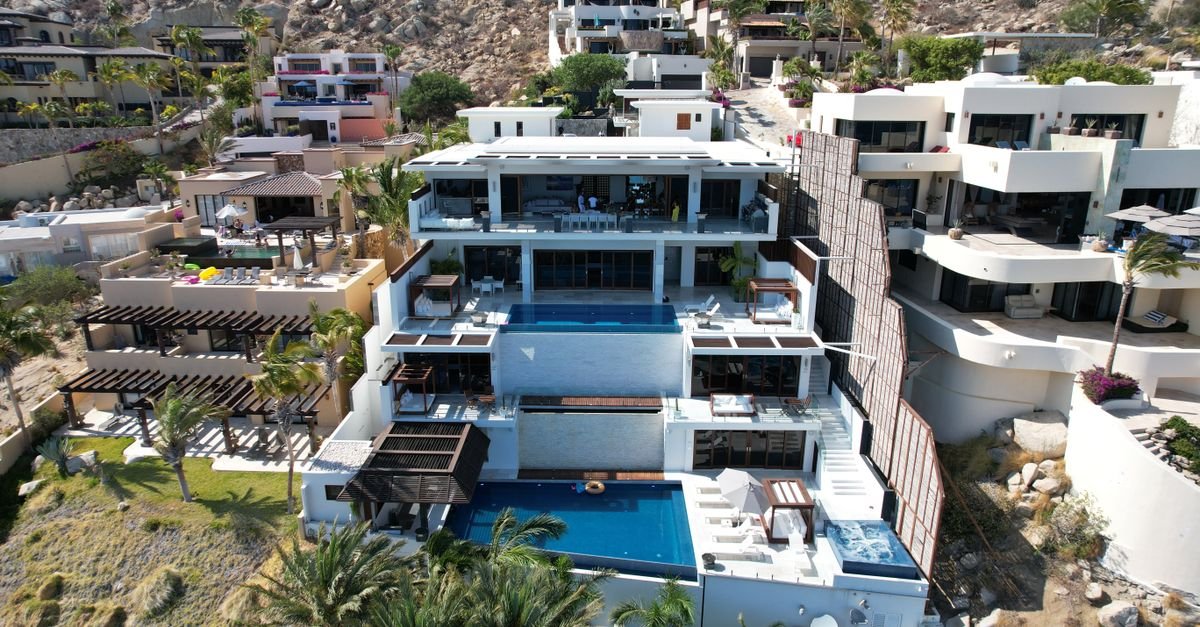
Understanding the financing options for Cabo property purchases can make your dream of owning a slice of paradise much more attainable. With breathtaking views, pristine beaches, and a thriving real estate market, Cabo San Lucas offers diverse opportunities for home buyers and investors alike. Exploring these financing avenues is essential to securing your ideal property in this stunning locale.
Key Takeaways
- Financing options for Cabo property purchases include cash buying, traditional mortgages, and seller financing.
- Down payments can vary significantly between options, typically ranging from 20% to 50% depending on the buyer’s financial profile.
- Local banks and international lenders may have different requirements for financing, so comparing terms is crucial.
- Working with a local real estate agent who understands the Cabo market can streamline the financing process.
- Real estate in Cabo delivers opportunities for appreciation, especially in popular areas like the Los Cabos Corridor and San Jose del Cabo.
Table of Contents
- Financing Options for Cabo Property Purchases
- Exploring Cash Purchases
- Traditional Mortgages: What to Expect
- Seller Financing Options
- Comparing Local vs. International Lenders
- Understanding Down Payment Requirements
- Timing Your Property Purchase
- Tips for a Smooth Financing Process
- What to Avoid in Cabo Property Financing
- Working with Real Estate Professionals
- Exploring Stunning Properties in Cabo
- Frequently Asked Questions
Financing Options for Cabo Property Purchases
When considering a property purchase in Cabo San Lucas, potential buyers have several financing options at their disposal, each tailored to different needs and financial situations. Understanding the nuances of these options is essential for a successful investment in this thriving market, known for its stunning locations like Medano Beach and the Cabo San Lucas Marina.
Cash Purchases
Cash purchases are straightforward and often preferred in Cabo real estate transactions. Without the need for mortgages, buyers can expedite the process significantly, often securing properties more quickly. Cash offers can be particularly appealing to sellers, making negotiation smoother and potentially yielding a better purchase price. Depending on the property type, prices can vary widely; for instance, a beachfront condo near Chileno Bay can start around $300,000, while luxury villas may exceed $2 million.
However, cash buyers should weigh this option against liquidity concerns. Investing a significant amount of capital raises questions about available funds for emergencies or other investments. Furthermore, paying cash forfeits any potential leverage benefits that financing could provide.
Mortgages
For those unable or unwilling to make a full cash payment, traditional mortgages remain a viable option. While local banks offer mortgage solutions, understanding that some foreign buyers often must seek financing through U.S. financial institutions is crucial. Mortgage rates can fluctuate, typically ranging from 4% to 7%, depending on the lender and the buyer’s creditworthiness. Buyers should be prepared to provide documentation that demonstrates financial stability and may need to pay a down payment of at least 20%.
Mortgages enable buyers to spread out payments over time, facilitating the acquisition of higher-value properties without immediate full payment. However, the approval process can be lengthy, and closing costs should be anticipated, often costing 2% to 5% of the property price. Consequently, this option demands careful consideration of one’s long-term financial strategy and the associated commitments involved.
Private Lending
Private lending has surfaced as an alternative, particularly for investors seeking flexibility and speed. This method involves securing funds from private individuals or companies, often bypassing the stringent requirements of traditional banks. Terms can be negotiable and typically yield quicker access to capital, making this an attractive option for quick-turnover investments or renovations. However, interest rates might be higher than traditional financing, often beginning at around 8%.
Understanding the local real estate landscape—characterized by notable attractions such as El Arco de Cabo San Lucas and diverse property types—will greatly inform financing decisions. Each financing option has distinct pros and cons, hence the importance of aligning them with personal investment goals and market conditions. Connecting with local experts can provide deeper insights, ultimately facilitating a smoother purchasing experience.
Exploring Cash Purchases
Buying a property in Cabo San Lucas with cash can be a particularly appealing option for both homebuyers and investors. One of the most significant advantages of this approach is the ability to completely avoid interest rates, which can save you thousands over the life of a mortgage. In a competitive market like Cabo, using cash can also provide you with greater negotiating power. Sellers often favor cash buyers since purchases can close quickly, facilitating smoother transactions without the complications of financing contingencies.
In Cabo, typical cash purchase scenarios often involve a range of properties from luxury beachfront villas to modest condos. Waterfront properties near Medano Beach or the Marina can command prices starting around $500,000 for smaller units, while larger homes or lots can exceed several million dollars, particularly if they boast views of El Arco de Cabo San Lucas. Many buyers opt for cash in markets that exhibit constant growth, where the appeal of immediate ownership outweighs the opportunity costs of tying up a significant amount of liquid assets.
Types of Properties Commonly Purchased with Cash
- Luxury beachfront villas (e.g., Chileno Bay, Costa Azul Beach) starting around $2 million.
- Condos in urban developments close to the Cabo San Lucas Marina, ranging from $300,000 to $800,000.
- Commercial properties in the Plaza San Lucas area, with prices varying widely but generally starting at $1 million.
- Investment properties in the Los Cabos Corridor, often purchased for vacation rentals.
However, purchasing a property outright comes with its own set of challenges. The most significant downside is the opportunity cost associated with tying up a large sum of cash. Funds that could be invested in diversified portfolios or used for other investments are effectively locked into real estate. Furthermore, while holding cash offers many advantages, the liquidity can impact future financial flexibility, making it crucial to carefully evaluate your financial situation and long-term goals before proceeding.
| Property Type | Typical Price Range | Common Locations |
|---|---|---|
| Luxury Villas | $2M – $5M+ | Chileno Bay, Costa Azul Beach |
| Condos | $300K – $800K | Near Marina, Medano Beach |
| Commercial Properties | $1M+ | Plaza San Lucas |
Traditional Mortgages: What to Expect
For buyers interested in securing traditional financing for properties in Cabo San Lucas, understanding how mortgages work in this unique market is essential. Compared to other regions, lending practices for purchasing real estate in Baja California Sur can vary. Traditional banks and mortgage companies, including both local financial institutions and some U.S. banks with international divisions, provide loans with varying terms, typically ranging from 10 to 30 years. These loans often have either fixed or variable interest rates, which can significantly affect your monthly payments.
Most lenders will require a down payment between 20% and 50% of the property’s purchase price. For example, if you’re eyeing a charming villa in the vibrant area near Medano Beach priced at $500,000, you might need to prepare a down payment that starts at $100,000 and could go as high as $250,000. The required down payment often depends on the buyer’s creditworthiness and the property’s characteristics. Buyers should budget not only for the down payment but also for additional costs associated with financing, including closing costs, which usually amount to 4-7% of the purchase price.
Standard Financing Conditions
Obtaining a mortgage in Cabo requires certain documentation and financial verifications. Buyers will typically need to provide proof of income, which can include recent pay stubs, tax returns, and bank statements. Lenders will conduct credit checks to assess your financial stability, and it’s advisable to keep your credit score above 700 to qualify for better rates. An appraisal of the property will also be necessary, ensuring that its market value aligns with the loan amount. This appraisal process can take anywhere from one to two weeks, depending on the lender’s requirements and scheduling.
- Potential down payments range from 20% to 50%.
- Loan terms typically available between 10 to 30 years.
- Documentation includes proof of income and credit history.
- Appraisal processes may last 1-2 weeks, depending on various factors.
Understanding these aspects of traditional mortgages will prepare you for a smoother buying process as you seek your slice of paradise in Cabo San Lucas, whether near the stunning views of El Arco or the quintessential charm of the Cabo San Lucas Marina.
Seller Financing Options
Seller financing presents a practical alternative for buyers interested in properties in Cabo San Lucas. This method allows purchasers to make monthly payments directly to the seller instead of securing a conventional mortgage from a bank or lender. Generally, the terms of seller financing can vary, but they often include a down payment, an interest rate, and a payment schedule. Buyers typically find themselves negotiating terms that often reflect
Comparing Local vs. International Lenders
Understanding your financing options when purchasing property in Cabo San Lucas is essential. Buyers often have to choose between local Mexican banks and international lenders, each with its own set of advantages and challenges. Local lenders can provide a more tailored approach, particularly for properties in high-demand areas such as the Los Cabos Corridor and Playa del Amor.
Working with local banks like Banorte and HSBC Mexico can be beneficial due to their familiarity with the Cabo real estate market. These institutions often have a clearer understanding of property valuations and trends in this tourist haven, providing competitive rates and financing packages. For example, local banks may offer interest rates starting around 8% for financing options over 15 years, which can be more accessible for buyers investing in a second home or rental property in the region.
Conversely, international lenders may offer attractive financing terms such as lower interest rates or longer payback periods, which can be appealing for expatriates or non-resident buyers. However, they might not fully grasp the nuances of the local property market, leading to challenges in appraisals or installing additional costs related to foreign ownership laws. Additionally, many international lenders require a substantial down payment—often around 30% to 40%—which could limit some buyers’ options.
- Local lenders: Better understanding of local market trends.
- International lenders: Potentially lower interest rates but higher down payments required.
- Timeline: Local bank approvals can be quicker, often taking 30 to 45 days.
- Property types: Both lenders typically finance residential properties, while commercial financing can be more complicated through international banks.
Ultimately, the best option depends on your individual circumstances, including your financial situation and how involved you plan to be in the local real estate market. Exploring options with both local and international lenders can provide insight into what works best for your Cabo dream home.
Understanding Down Payment Requirements
In Cabo San Lucas, the down payment requirements for property purchases can significantly vary based on the type of financing chosen. Generally, for conventional loans issued by U.S. lenders, expect to place a down payment ranging from 10% to 20% of the property’s purchase price. For those looking at properties near iconic landmarks such as El Arco de Cabo San Lucas or the bustling Cabo San Lucas Marina, a 20% down payment can position buyers to receive more favorable loan terms, including lower interest rates and reduced monthly payments. This not only strengthens the buyer’s credentials in the eyes of lenders but also minimizes the lifetime cost of the mortgage.
If opting for a lower down payment, typically around 5% to 10%, it’s essential to consider the implications. While it can make ownership more accessible, this route often requires private mortgage insurance (PMI). PMI can add between $100 to $200 monthly to your mortgage payment, depending on the total loan amount. With Cabo properties ranging from $300,000 to exceed $1 million in desirable areas like Medano Beach or San Jose del Cabo, the costs associated with PMI can quickly accumulate and should be factored into your financial planning.
Comparative Down Payment Options
| Financing Option | Typical Down Payment | Private Mortgage Insurance (PMI) | Interest Rate Benefits |
|---|---|---|---|
| Conventional Loans | 10% – 20% | No (above 20% down) | Lower Rates with Higher Down Payment |
| FHA Loans | 3.5% | Yes | Higher Rates |
| VA Loans | 0% | No | Competitive Rates |
Understanding these factors is essential for anyone exploring properties in Cabo, whether near the tranquil Costa Azul Beach or the protected waters of Cabo Pulmo National Park. Having a solid grasp of down payment requirements allows buyers to strategize and secure financing that aligns with their financial goals, ultimately making the dream of owning a piece of this stunning paradise a reality.
Timing Your Property Purchase
Timing is everything when it comes to purchasing property in Cabo San Lucas. The real estate market here exhibits noticeable seasonal patterns, influenced largely by tourism flows. Peak tourism season, running from mid-December through April, often sees heightened demand for properties. During these months, prices can swell by 10-20% compared to the quieter off-season, a result of increased rental income potential and investor competition. Conversely, the months from May to November, particularly during the summer, typically yield lower prices as both local sellers and vacationing buyers are less active.
Local events can further impact the market. Notable happenings such as the Bisbee’s Black & Blue Fishing Tournament in October or the annual Cabo San Lucas International Film Festival can attract a surge of visitors and potential investors. For instance, during these events, inquiries about properties often spike, creating a sense of urgency that can inflate prices significantly—sometimes by as much as 15% in the weeks leading up to such events. Keeping track of the annual calendar and aligning your buying strategy with these peaks can give you a crucial advantage.
Appreciation Rates in Cabo San Lucas
The appreciation rate of property in Cabo is compelling, with averages typically hovering around 5-8% annually over the last decade, making it an attractive market for long-term investments. Areas like Medano Beach and the Los Cabos Corridor have shown even higher appreciation due to their prime locations and amenities, appealing to both foreign buyers and locals alike. For instance, high-demand areas near El Arco or Chileno Bay have seen price increases that outstrip average returns, with some properties appreciating over 10% in just two years. Understanding these trends will not only help you assess the right time to buy, but it will also allow you to identify which areas might yield the best returns.
- Peak season for buying: Mid-December to April
- Off-peak season with lower prices: May to November
- Notable local events impacting prices: Bisbee’s Black & Blue Tournament (October), San Lucas Film Festival (November)
- Average appreciation rate: 5-8% annually
- High-demand areas to watch: Medano Beach, Los Cabos Corridor, Chileno Bay
By considering the timing of your purchase alongside these trends and events, you can position yourself to make a more informed decision and secure a better deal on your dream property in Cabo.
Tips for a Smooth Financing Process
Purchasing property in Cabo San Lucas is an exciting endeavor, but navigating the financing process requires prior preparation. Buyers should start by gathering essential documents, including bank statements, tax returns from the last two years, proof of income, and any current debts. Understanding your financial landscape is critical; an accurate picture of your debt-to-income ratio can help determine how much you can borrow. Generally, lenders prefer a ratio below 43%. For a property valued at around $500,000, this means you should ideally have a total monthly debt obligation of $2,150 or less to qualify for conventional financing.
Getting pre-approved for a mortgage is a significant step that can streamline your property search. Pre-approval not only provides clarity on your budget but also enhances your standing as a buyer. Sellers in sought-after areas like Medano Beach and Los Cabos Corridor often prioritize offers from pre-approved buyers, knowing they are serious and financially secure. The pre-approval process typically takes one to three days, and it can give you a competitive edge in a fast-moving market, where properties near El Arco de Cabo San Lucas can generate multiple offers.
Maintain Open Lines of Communication
Collaborating closely with your real estate agent and mortgage lender is crucial for a smooth financing experience. Establish a routine for updates; a quick check-in every week can keep everyone aligned on timelines and expectations. If potential issues arise—such as underestimating closing costs or property appraisals coming in lower than expected—early communication can help you devise solutions without disrupting your purchase timeline. Close partnerships with local experts familiar with the Cabo market, including popular neighborhoods like San Jose del Cabo or Costa Azul Beach, can provide insights into fair market value and appropriate financing options.
- Gather documents: tax returns, income proof, debts
- Understand your financial landscape and debt-to-income ratio
- Seek pre-approval to enhance buyer credibility
- Establish regular communication with agents and lenders
By taking these critical steps, you can help ensure a smoother financing process and focus more on the exciting aspects of buying property in Cabo, such as where you’ll set up that beachfront barbecue or how to enjoy sunset views from your new terrace.
What to Avoid in Cabo Property Financing
Buying property in Cabo San Lucas can be an exciting venture, yet navigating the financing landscape requires a careful approach. One of the most significant missteps buyers often make is skipping the pre-approval process for a mortgage. Pre-approval provides a clearer picture of your budget and strengthens your negotiating position. Without it, you risk overextending your finances or misunderstanding the market dynamics in areas such as the Los Cabos Corridor, where prices can fluctuate. Properties around Medano Beach may range from $300,000 for a modest condo to several million for luxury villas, making it vital to know what you can comfortably afford.
- Skipping pre-approval can lead to budget confusion.
- Understanding your financing options is crucial to making informed decisions.
Avoiding high-interest loans is another crucial consideration. In Cabo, many lenders may offer financing options with interest rates ranging from 6% to 9%, which can lead to exorbitant costs over time if not chosen wisely. If you find yourself in a position where a higher interest rate seems your only option, assess the long-term implications. Tools like online loan calculators can help you estimate total repayment amounts, illustrating how a seemingly minor interest difference can result in thousands of dollars in additional payments.
Additionally, thorough due diligence on the property’s title and ownership history cannot be overstated. Purchasing a property without a clear title can result in significant legal headaches, especially in a foreign country. Working with a reputable real estate agent in Cabo San Lucas who understands the local market and legal framework is vital. Properties near popular spots such as The Arch of Cabo San Lucas or near Tommy Bahama Restaurant often demand higher prices, but the potential investment could sour if there are clouds on the title. Engaging a local attorney to verify these details may seem like an added expense, but it can safeguard your investment over the long run.
Working with Real Estate Professionals
Engaging with local real estate professionals can significantly enhance your property search in Cabo San Lucas. These experts possess intimate knowledge of the market, from emerging neighborhoods like San Jose del Cabo, celebrated for its charming art district, to the bustling Marina area with upscale dining and shopping. With property prices typically ranging from $300,000 for a beachfront condo to over $3 million for luxury villas, a knowledgeable agent can help identify options that match your budget and lifestyle preferences.
Beyond simply presenting listings, a local agent offers invaluable insights into prevailing market trends and financing options tailored to your needs. They can articulate the nuances of securing a mortgage in Mexico, where foreign buyers often face different regulations compared to domestic citizens. Knowing the types of financing available—such as bank financing, seller financing, or even owner financing—allows you to choose strategies that fit your financial situation. A skilled agent will also assist in making competitive offers, ensuring you understand how your financing choice can influence negotiations.
The Importance of a Local Attorney
Working with a local attorney specialized in real estate can further protect your interests during the buying process. Property laws in Mexico can vary significantly from those in the U.S. or Canada, and navigating them without legal counsel can lead to costly mistakes. An attorney can ensure your transaction adheres to local regulations and help you understand essential documentation required for closing, including the escritura (deed) and the fideicomiso (bank trust), which are crucial for non-Mexican buyers. Fees for legal services generally range from 1% to 3% of the property value, a wise investment for peace of mind.
- Local agents can guide you through financing options.
- They help identify properties that meet your criteria.
- Agents assist with competitive offer strategies.
- Employing a lawyer familiar with local laws mitigates risks.
Consider partnering with these professionals to simplify the property buying process in Cabo San Lucas. Their expertise can transform a complex undertaking into a smooth experience, allowing you to focus on finding your dream home near stunning locations like El Arco de Cabo San Lucas or Medano Beach.
Exploring Stunning Properties in Cabo
Cabo San Lucas presents a unique opportunity for property buyers, especially in coveted coastal areas like Medano Beach and San Jose del Cabo. Both locations offer a range of residential and commercial properties that cater to different lifestyles and investment goals. For instance, a three-bedroom beachfront condo at Medano Beach may list around $800,000, while properties in San Jose del Cabo can vary significantly based on proximity to the ocean, with prices ranging from $400,000 to well over $2 million for luxury estates.
Investors can find attractive financing options in Cabo. Many local banks and financial institutions offer mortgage products tailored for foreigners, sometimes with down payments as low as 20%. For example, if you consider a $500,000 home, a 20% down payment would amount to $100,000, with monthly payments potentially starting around $2,500, depending on interest rates and the term of the mortgage. Furthermore, some new developments may even provide flexible financing or incentives to help buyers close deals more easily, which is worth exploring when shopping for properties.
Lifestyle Benefits of Owning in Cabo
Owning property in Cabo is not just about having a place in the sun; it’s about embracing a vibrant lifestyle. Residents enjoy year-round access to world-renowned beaches, with Medano Beach known for its warm waters and tranquil atmosphere, making it ideal for swimming and water sports. The proximity to the Cabo San Lucas Marina opens doors to a plethora of dining and entertainment options, from casual eateries like the Tommy Bahama Restaurant to upscale fine dining establishments.
Additionally, the region is rich in outdoor activities, whether it’s snorkeling at Cabo Pulmo National Park or enjoying picturesque sunsets at Lover’s Beach. Homeowners can partake in a variety of cultural events, art walks in San Jose del Cabo, and numerous festivals throughout the year. This blend of natural beauty and engaging community events makes Cabo not only a desirable place to invest but also a fantastic destination to call home.
Frequently Asked Questions
What are the primary financing options available for purchasing property in Cabo San Lucas?
Buyers can explore several financing options, including traditional mortgages through local banks, developer financing, and cash purchases. Traditional mortgages generally require a down payment of 20-30% and have interest rates between 6-8%. Developer financing often provides more flexible terms, appealing to international buyers.
Is it possible to secure a mortgage in Cabo San Lucas as a foreign buyer?
Yes, foreign buyers can obtain mortgages in Cabo San Lucas, but the process may differ from their home country. Many banks require proof of income, a decent credit score, and a down payment of 30% or more. It’s advisable to consult with local financial advisors familiar with the intricacies of Mexico’s property financing.
What is the average interest rate for mortgages in Cabo San Lucas?
As of 2026, interest rates for mortgages in Cabo San Lucas typically range between 6% and 8%. Rates can vary based on individual financial profiles and the lender’s terms. Always shop around for the best rates to maximize your investment.
Are there any special financing programs for first-time home buyers in Cabo?
First-time home buyers in Cabo may not find specific government-driven programs like in other countries. However, some developers may offer unique financing plans or incentives, particularly in newly built communities around the Los Cabos Corridor or near Medano Beach.
How do property taxes affect financing options in Cabo San Lucas?
Property taxes in Cabo San Lucas are typically low, averaging around 0.1-0.2% of the property’s assessed value. While this expense may not directly influence financing options, understanding ongoing costs is vital for budgeting and ensuring long-term affordability.
What documentation is required when applying for financing in Cabo?
Documentation requirements can vary by lender, but common documents include proof of income, tax returns, a copy of your passport, and a credit report. Some lenders may also request bank statements and a letter of reference to assess the borrower’s financial stability.
How long does the mortgage approval process take in Cabo?
The mortgage approval process in Cabo San Lucas typically takes between four to six weeks. Factors such as the lender’s processing speed and the completeness of your paperwork can affect the timeline. Expect some variation, especially during peak real estate seasons.
What are the advantages of cash purchases in Cabo real estate?
Purchasing property in cash can simplify the buying process. Cash buyers in Cabo benefit from quicker closings, fewer fees associated with financing, and stronger negotiating power. This is particularly advantageous for prime properties near El Arco de Cabo San Lucas or Costa Azul Beach.
Explore stunning properties in Cabo today!
Deja una respuesta